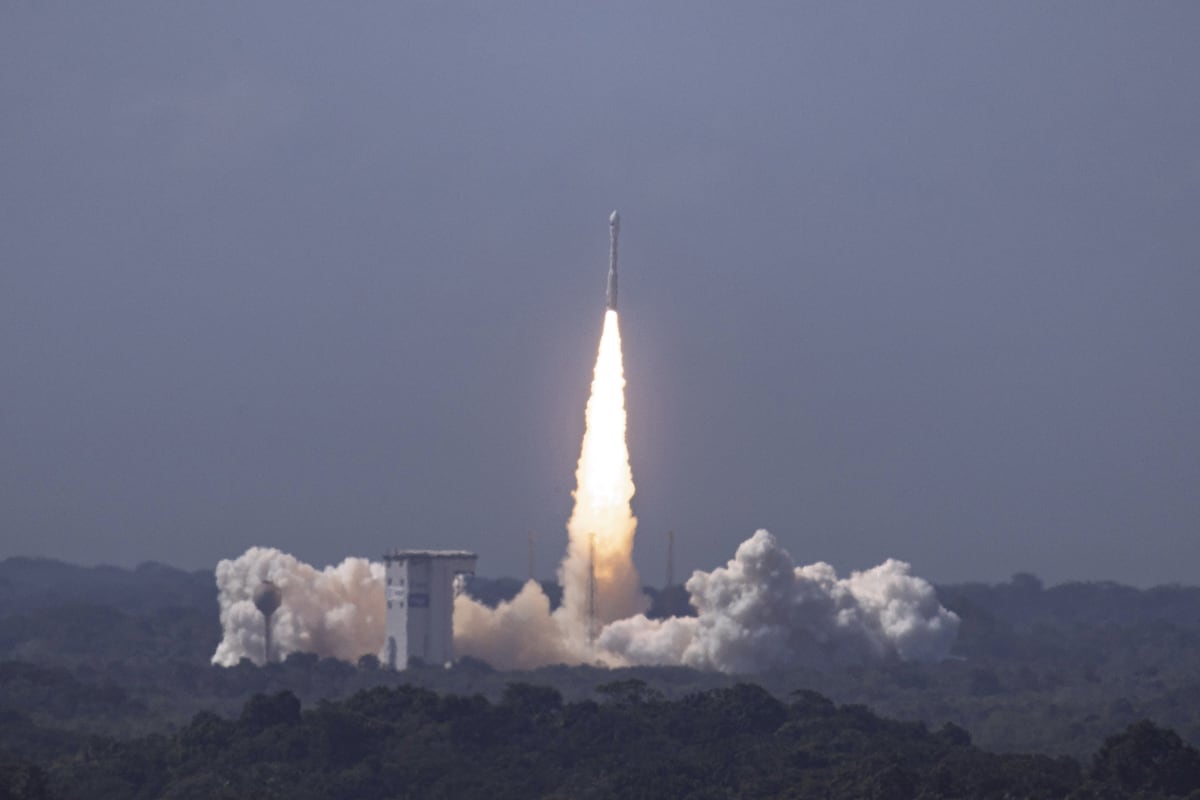
PARIS — The number of satellites sent to orbit to supply militaries and defense departments with intelligence, surveillance and reconnaissance data is on track to increase more than fourfold over the next decade, according to a new market forecast from the consultancy Novaspace.
The projection was presented Tuesday at the Space Defense and Security Summit in Paris by Novaspace Chief Executive Officer Pacôme Révillon, who laid out a decade-by-decade comparison that shows the segment shifting from a niche capability to a core component of military planning.
A Fourfold Jump in Launch Demand
Novaspace's figures put the coming decade at 2,306 defense-owned ISR satellites launched into orbit during the 2026–2035 period. That compares with 485 such satellites launched across the entire decade ending in 2025 — a difference of more than four times, and one that would reshape launch manifests, manufacturing lines and ground-station architectures alike.
The consultancy's central finding is not simply that more ISR satellites are coming, but where they are coming from. Defense-owned systems, rather than commercially procured imagery alone, are expected to drive the future market in this segment. That distinction matters: government-owned constellations imply sustained public budgets, sovereign supply chains and long-term industrial commitments rather than one-off service contracts.
If the forecast holds, the ramp would represent one of the steepest sustained build-outs in the modern space economy, with hundreds of additional spacecraft requiring launch slots, sensor payloads, downlink capacity and analytics pipelines over a relatively short span.
Why the Ukraine War Changed the Calculus
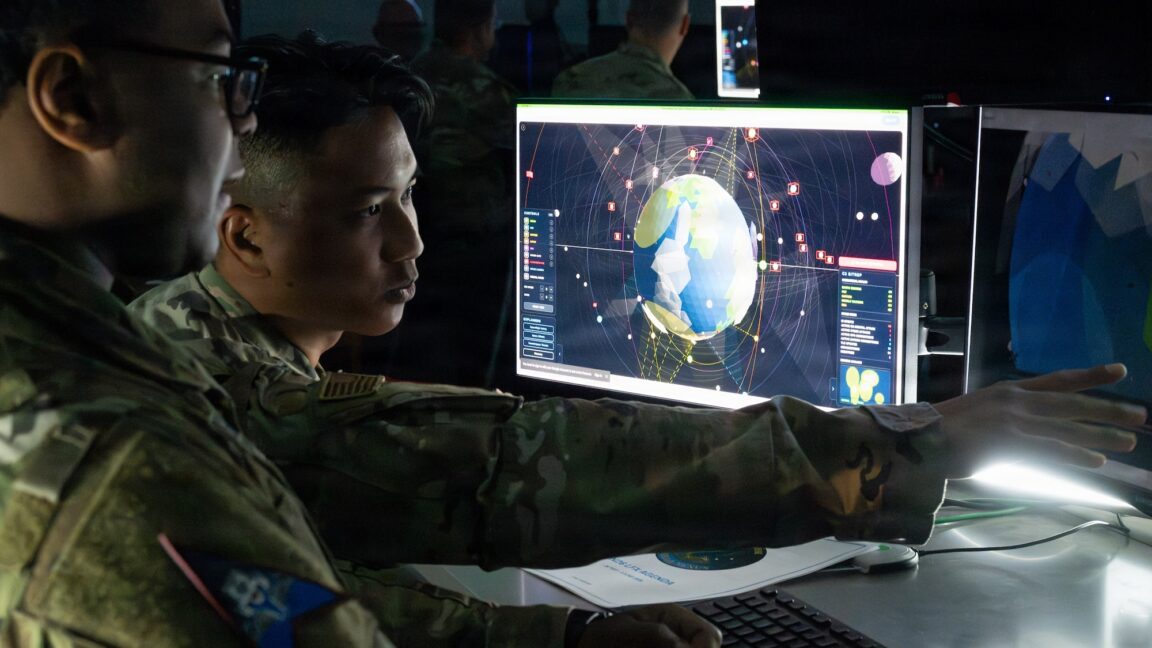
Révillon's presentation tied the expected surge directly to recent conflict. The war in Ukraine has underscored how much space-based intelligence contributes on the battlefield, turning orbital imagery and signals collection from a supporting function into an operational necessity for commanders who need to see movement, target sets and terrain in near real time.
That lesson has been absorbed well beyond the two belligerents. Governments that previously relied on allied data-sharing arrangements have begun to treat space-based ISR as a matter of national capability rather than an outsourced convenience — a shift that shows up directly in the forecast's emphasis on defense-owned satellites.
The Assured Access Problem
A second driver cited in Paris was more specific and, for many capitals, more uncomfortable. A brief halt in data sharing by the United States in March 2025 demonstrated to allied governments the risk of depending on another nation's constellations for time-sensitive intelligence.
The episode did not need to be long to be instructive. When access to space-based intel can be interrupted by political or policy decisions made elsewhere, the argument for sovereign or at least contractually guaranteed capacity becomes considerably stronger. That logic cuts across large and small defense budgets alike, and it helps explain why the forecast tilts toward government-owned rather than purely commercial fleets.
Assured access also implies resilience requirements that go beyond raw satellite counts: redundant ground segments, secure data links, rapid replenishment options and the ability to keep collecting through interference or denial attempts.
Commercial Providers Ride the Wave
The push for sovereign capability has not shut commercial operators out of the picture. Novaspace's assessment indicates the surge has been a boon to companies that sell ISR satellite services, with Finland's ICEYE cited as a prominent example of a commercial provider benefiting from the heightened demand.
The relationship between government and industry in this segment is increasingly layered. Defense ministries may own constellations outright, purchase imagery and analytics as a service, or pursue hybrid models in which commercial spacecraft supplement government-owned systems during surge periods or over specific regions of interest.
- Defense-owned satellites are expected to lead the market, giving governments direct control over tasking and dissemination.
- Commercial ISR providers, including ICEYE, are positioned to gain as demand for orbital sensing expands.
- Hybrid arrangements offer a bridge for states that want assured access without building every capability in-house.
An Escalating Domain
The ISR build-out is unfolding against a broader militarization of orbit. In a related development, U.S. Air Force Secretary Troy Meink revealed that the service has deployed on-orbit space control weapons, though he did not offer details on the type of weapon involved.
That disclosure sits alongside the ISR forecast as a reminder that the same orbital environment hosting thousands of new sensing satellites is also becoming a contested one. More capable surveillance fleets heighten the incentive for adversaries to develop counter-space options, and counter-space developments in turn strengthen the case for redundancy and assured access — the very forces Novaspace expects to propel launch demand.
The combination suggests the next decade's space market will be shaped not only by how many satellites governments want, but by how confident they are that those satellites will remain available when they are needed most.
What to Watch
Several indicators will determine whether the fourfold projection is realized. Launch cadence and the availability of affordable rideshare and dedicated launch capacity remain gating factors, as does the industrial capacity to produce sensors and spacecraft buses at scale. Budget cycles across allied capitals will test whether stated intentions translate into contracted orders.
Equally important is how the market splits between government-owned and commercially provided capability. If the March 2025 data-sharing interruption continues to shape thinking in allied defense ministries, the tilt toward sovereign constellations may prove even sharper than Novaspace's baseline scenario. If instead hybrid procurement models mature quickly, commercial operators could capture a larger share of the 2,306 satellites projected for the coming decade.
Either way, the direction of travel is clear. Space-based intelligence has moved from a specialized enabler to an assumption underpinning military operations, and the launch numbers Novaspace presented in Paris suggest the orbital layer of that assumption will be built out at a pace with few precedents.
This article is based on reporting by Defense News. Read the original article.
Originally published on defensenews.com