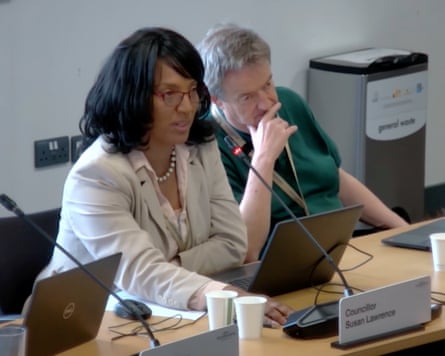
A councillor who promoted the collapsed HyperVerse cryptocurrency scheme has been elected to Wolverhampton city council and now sits on its audit and risk committee, according to reporting by the Guardian. The case puts renewed attention on how public bodies assess reputational risk, disclosures and public confidence in financial oversight.
Susan Lawrence, a Reform UK councillor, was one of the main UK promoters of HyperVerse, the Guardian reported. US court documents described HyperVerse as an alleged pyramid and Ponzi scheme that cheated investors worldwide out of $1.89 billion. Lawrence has not personally been accused of wrongdoing by authorities, a distinction that is central to understanding the reporting.
HyperVerse operated across the US and UK from 2020 to 2022 and also targeted investors in Asia, Africa and the Pacific, according to the report. After the scheme collapsed, many participants were unable to access funds. Some people who had taken out bank loans to buy packages in the scheme said they felt suicidal; the Guardian also reported cases of self-harm.
A role overseeing governance and risk
Lawrence is a member of Wolverhampton city council’s audit and risk committee. The committee independently reviews governance and risk management and oversees financial reporting connected to the council’s multimillion-pound budget, the Guardian said.
Committee membership does not mean a councillor controls the authority’s day-to-day finances. But audit and risk committees carry a particular public-facing responsibility. They are expected to scrutinize whether an organization identifies risks, maintains sound controls and produces reliable financial information. That makes past associations with a collapsed investment scheme especially sensitive, even where no individual finding of misconduct has been made.
The issue is therefore not simply the history of a cryptocurrency venture. It is also a test of how a local authority, political parties and voters weigh conduct that may create concern without amounting to a formal allegation or conviction against the officeholder.
The Guardian reported that Lawrence promoted HyperVerse and later variations of the project even after the UK Financial Conduct Authority issued a consumer warning in 2021. The regulator said the firm may have been promoting financial services or products without permission and advised consumers to avoid dealing with it and to beware of scams.
What the HyperVerse episode involved
The report describes HyperVerse as a scheme promoted through online videos, webinars and community presentations. Lawrence participated in promotional material aimed at marketing the project to the public and recruiting participants, according to the Guardian.
By 2022, the report said, she addressed HyperVerse community members who were concerned because they could no longer access their invested money. Members were later encouraged to move to HyperNation after difficulties withdrawing funds from HyperVerse, according to the Guardian’s account of a promotional video.
Cryptocurrency promotions can make it harder for prospective participants to distinguish technological language from financial substance. Terms associated with tokens, platforms and online communities can give a project an air of innovation, while the essential consumer questions remain straightforward: What is being bought? Where does the promised value come from? Can the asset be sold or withdrawn? Is the entity authorized to offer regulated products? And what protections exist if things go wrong?
The HyperVerse case is a harsh example of why those questions matter. The Guardian’s report describes investors who could not access their money after the scheme’s collapse, including people who had borrowed to participate. The personal impact described by victims goes far beyond a failed speculative investment.
Why financial warnings matter
The Financial Conduct Authority warning cited in the report was not a finding that Lawrence committed an offence. It concerned a firm that may have been promoting financial services or products without the regulator’s permission. Still, such warnings serve an important consumer-protection function: they signal that a business may fall outside the normal framework of authorization and oversight.
Consumers encountering high-return investment pitches should treat authorization status as a starting point, not a complete safeguard. They should also be alert to pressure to recruit others, urgency around deposits, unclear explanations of how returns are generated and obstacles to taking money out. Borrowing to invest in a speculative or poorly understood scheme adds another layer of risk.
For people already affected by a collapsed scheme, shame and isolation can worsen the harm. The Guardian’s reporting on distress and self-harm underscores the need for victims to seek support from trusted people and appropriate professional or emergency services if they are in immediate danger. Financial losses can be devastating, but they should not be faced alone.
A wider question of public trust
The story also reaches beyond the individuals involved. Audit and risk functions are meant to reassure residents that public money is subject to scrutiny. Confidence in those functions depends not only on formal rules but also on whether the people involved are seen as capable of exercising independent judgment.
Political parties and councils face difficult choices in cases where an officeholder’s past is publicly documented but authorities have made no personal accusation. Due process and accurate language are essential. So is a willingness to confront whether the facts disclosed are compatible with the responsibilities of a particular role.
The Guardian’s reporting leaves a clear public-interest question: how should a councillor’s previous promotion of an alleged cryptocurrency fraud be considered when that councillor participates in oversight of a major local authority’s financial reporting and risk management?
That question cannot be answered by cryptocurrency rhetoric alone. It requires transparent disclosures, careful governance and accountability to the people whose money and trust the council is responsible for safeguarding.
This article is based on reporting by The Guardian. Read the original article.
Originally published on theguardian.com